Hyperliquid Strategies Inc, the NASDAQ-listed HYPE treasury that trades as PURR, has applied to become a futures commission merchant. The company disclosed the filing in its third-quarter res
Hyperliquid Strategies Inc, the NASDAQ-listed HYPE treasury that trades as PURR, has applied to become a futures commission merchant. The company disclosed the filing in its third-quarter results release on November 5, 2026, alongside $620.6 million of net income for the quarter ended September 30. Approval would let a subsidiary carry US client accounts for permissioned markets deployed on Hyperliquid, the exchange whose token supplies most of the company’s balance sheet.
The two announcements arrived in the same document because they describe one strategy. “We deployed $802 million this quarter and filed an application to become a futures commission merchant,” chief executive David Schamis said in the release. “Those two moves are the same bet.”
The bet has two very different halves. One is a regulated intermediary business that does not exist yet and depends on an approval the company cannot schedule. The other is a $3.5 billion token position whose quarterly revaluation produced almost the entire profit.
What an FCM application does and does not mean
A futures commission merchant is the US category for a firm that accepts customer funds and executes futures and options orders. Registration runs through the Commodity Futures Trading Commission, and it is the licence a venue needs before it can hold American retail accounts rather than route them offshore.
Hyperliquid Strategies is not there. The release says a subsidiary “has filed an application to become a futures commission merchant,” and then sets the condition plainly: “Subject to regulatory approval, the FCM would carry US client accounts for permissioned markets deployed on Hyperliquid under HIP-3, allowing HSI to play a role in bringing perpetual futures to US customers within a regulated framework.” The same paragraph closes the door on expectations: “There can be no assurance as to the timing or outcome of the application or regulatory approval of permissioned HIP-3 markets.”
The markets the FCM would serve are also not live. HIP-3 is described as Hyperliquid’s stated intention to add deployer functionality, an optional set of features under which “independent operators would run their own market in a compliant manner, while the chain underneath would stay a neutral infrastructure layer.” A permissioned market operator, a registered intermediary and an approved rulebook are three separate prerequisites. As of November 5, the company has applied for one of them.
The application sits inside a broader push to move Hyperliquid’s perpetual futures into US regulated venues, a path NYSE owner ICE set out in its Trade[XYZ] deal at the end of October. An exchange listing and a brokerage licence solve different problems, and Hyperliquid Strategies is applying for the second.
That distinction matters for how the equity should be read. A filing is a statement of intent with a fee attached, not a revenue line, and the release gives no target date, no capital figure for the FCM subsidiary and no indication of how customer accounts would be margined or cleared.
A $620.6 million profit built on an $803 million mark
The income statement is more legible than the regulatory plan. Net income of $620.6 million included $803.0 million of net unrealized gains on HYPE tokens, a $15.3 million non-cash charge tied to the committed equity facility, and a $172.3 million provision for income taxes. Staking revenue and validator commissions contributed $12.3 million. Interest income added $1.0 million, and selling, general and administrative plus research spending came to $7.6 million.
Those lines reconcile to about $792.9 million of pre-tax income, which implies an effective tax rate near 21.7%. Remove the $803.0 million mark and add back the $15.3 million facility charge, and the operating core of the business, meaning staking income, interest and running costs, comes to roughly $5.2 million before tax. That is 0.8% of the reported bottom line.
The wording of the release matters here. Net income was “primarily comprised of” net unrealized gains on HYPE tokens, and unrealized is the operative term: no line in the document describes the mark as cash received. The tax provision, by contrast, does not reverse if the token price falls.
38.9 million tokens at a $56.35 average
The balance sheet is a single position with a treasury attached. Total assets were $3,764.3 million at September 30, of which $3,505.3 million was HYPE valued “based on a September 30, 2026 HYPE price of $90.99 per HYPE token,” representing about 38.52 million tokens. Cash and cash-like instruments were $254.6 million. Stockholders’ equity was $3,403.0 million and the company reports no debt.
Concentration works out to 93.1% of assets in one token, a figure the release does not state. The company’s own October 28 update puts the position slightly higher at 38.9 million tokens, accumulated at a blended cost of $56.35. Against that basis, the September 30 price implied about $1.35 billion of embedded gains, calculated as 38.9 million tokens multiplied by the $34.64 gap between the mark and the average cost.
Buying has been continuous. The quarter absorbed $785 million for 9.1 million tokens, lifting the treasury from 29.3 million at June 30. Since inception on December 2, 2025, the company has deployed $1,583.2 million to accumulate about 25.9 million tokens at an average of $61.13, a higher entry than the blended cost because staking and validator rewards now make up part of the total.
A $10.36 issue price and a $4.81 buyback
The equity side of the structure is where the arithmetic gets uncomfortable. Hyperliquid Strategies raised $1,578.4 million under its committed equity facility at an average issue price of $10.36 per PURR share. It has spent $27.9 million repurchasing about 5.8 million shares at an average of $4.81, a price 54% below what the facility was issuing at. In October the company tripled its share repurchase authorisation to $100 million as PURR traded below net asset value, and the buyback price of $4.81 shows how wide that discount had become.
Those two numbers describe a stock that has traded far under the price at which the vehicle sold paper. For existing holders, buying back at $4.81 is accretive in a way that issuing at $10.36 never was: each retired share concentrates the same token book into fewer claims. The release does not disclose the current share count or an NAV per share, so the size of that accretion cannot be derived from this document alone, but the direction is not ambiguous. The company does say it publishes an Adjusted Net Asset Value section on its investor site, updated outside the quarterly cycle, which is where that per-share figure would appear.
In the quarter itself the company spent $17 million to repurchase 2.7 million shares, an average near $6.30, and $802 million in total deployment against $911 million raised. That 88% deployment ratio leaves little idle capital, which is consistent with a $254.6 million cash balance against a $3.5 billion token position.
Staking revenue is small next to the mark
The operating businesses are real but modest. Staking revenue and validator commissions of $12.3 million against a $3,505.3 million token book works out to about 0.35% for the quarter, or roughly 1.4% annualized. That is the yield on the assets the company is levered to, and it is the only line in the release that resembles recurring revenue.
Hyperliquid Strategies also says its joint validator with Unit is now the largest non-Foundation validator on the network. The release attributes $834 million of value accruing to the Hyperliquid ecosystem in the twelve months to September 30, and notes that much of it reaches HYPE holders through programmatic buybacks. That figure carries a footnote stating it is based on public information and “has not been independently verified by HSI,” so it should be read as the company’s characterisation of the protocol’s economics rather than an audited number.
The gap between $834 million of ecosystem value and $12.3 million of quarterly staking income to this vehicle is the case for the FCM. A token holder captures buybacks. A registered intermediary captures fees on flow it carries. Only the second produces revenue that does not move with the mark.
What the current price does to the fourth quarter
HYPE traded at $76.84 at 00:15 UTC on November 6, down 8.2% in the preceding 24 hours, according to CoinGecko price data. At that level the 38.9 million tokens held as of October 28 are worth about $2.99 billion, against $3.54 billion at the September 30 mark. The difference, roughly $550 million, is unrealized and will land in the fourth-quarter income statement if the price stays here.
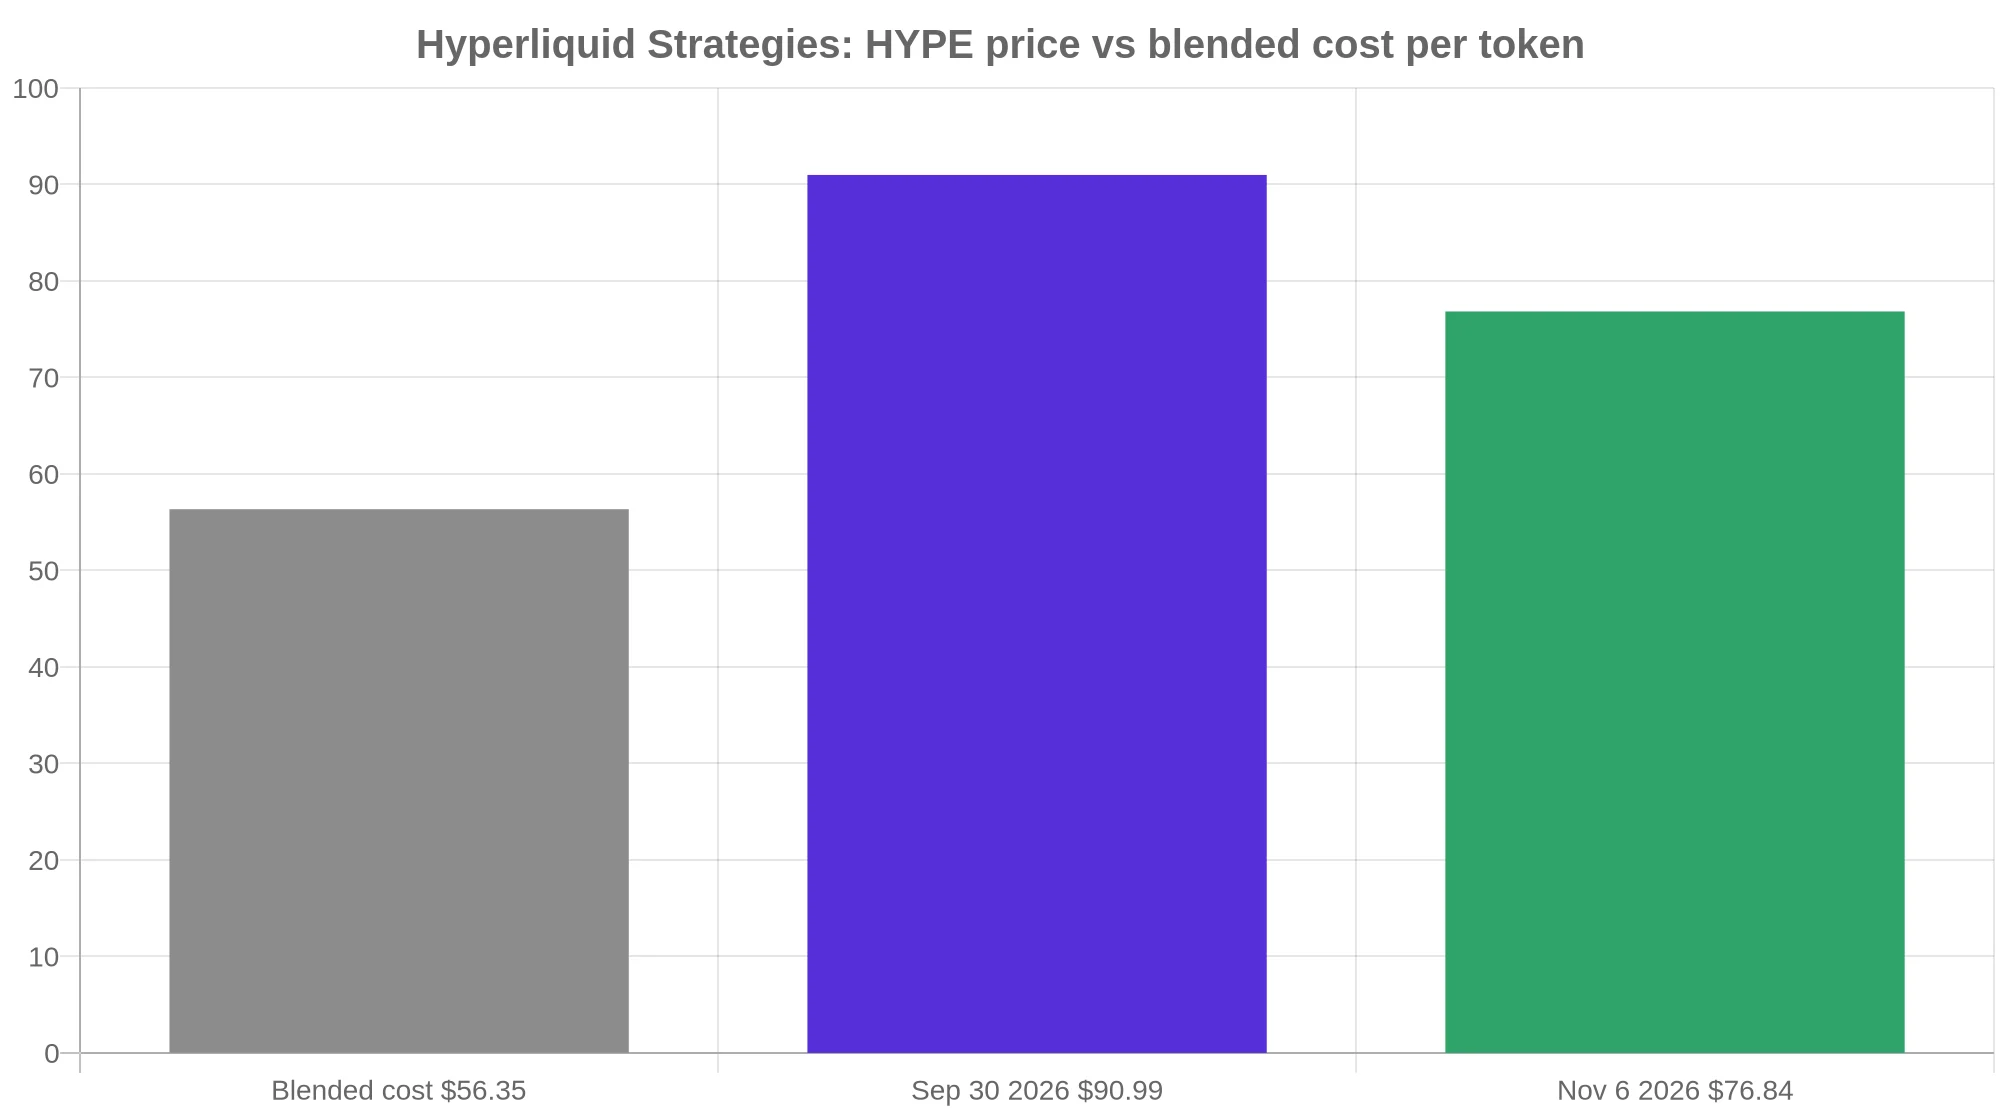
For scale, that swing is about 105 times the $5.2 million operating core calculated from the third quarter. A holder buying PURR for the FCM thesis is currently holding a leveraged HYPE position with a licensing option attached, and the reported earnings will keep tracing the token rather than the business until the application is decided.
Three things are worth watching, and none of them is a price target. The first is whether the FCM application produces a public comment period or an approval order, since either would move HIP-3 from intention to infrastructure. The second is whether Hyperliquid’s deployer framework goes live in a form that lets a permissioned market accept US accounts, because an FCM without markets to clear earns nothing. The third is the share count: if the facility keeps issuing at $10.36 while buybacks clear at $4.81, the per-share exposure to HYPE keeps changing for reasons unrelated to the token.
Schamis framed the strategy as one trade. “Owning HYPE is how we aim to capture economics associated with the Hyperliquid protocol; setting up an FCM is how we intend to help bring markets deployed on Hyperliquid onshore.” The quarter shows the first half working as designed, in marks. The second half is an application in a regulator’s queue, and the company’s own words put no date on it.