DefiLlama is the largest freely accessible data platform for decentralized finance (DeFi). It shows how much capital sits in crypto protocols such as Aave, Lido or Uniswap, how much these pro
DefiLlama is the largest freely accessible data platform for decentralized finance (DeFi). It shows how much capital sits in crypto protocols such as Aave, Lido or Uniswap, how much these protocols earn in fees, which stablecoins are in circulation and what yields pools are currently paying. The data is free, available without registration, and the methodology is public. On November 3, 2026, according to DefiLlama, $81.8 billion was locked in DeFi, 53.9 percent below the record of November 9, 2021. How to read TVL, fees, revenue, stablecoins and yields correctly, and where even experienced investors take a wrong turn, we show here using our own analysis of DefiLlama data.
DefiLlama at a glance: the key numbers
- On November 3, 2026, $81.8 billion sat in DeFi protocols, compared with $144.5 billion a year earlier.
- Ethereum accounts for $43.6 billion of that, or 53.2 percent; DefiLlama tracks 290 blockchains with locked capital.
- Measured in ether, the capital on Ethereum fell by only 7.8 percent since November 3, 2025; in dollars, by 46.9 percent.
- In the 30 days to November 2, 2026, users paid $2.27 billion in fees, of which $1.25 billion stayed with the protocols.
- Dollar stablecoins worth $296.5 billion were in circulation on November 3, 2026, with Tether (USDT) holding 60.2 percent of them.
- Of 2,654 yield pools with at least $1 million in deposits, half paid less than 2.17 percent a year.
DefiLlama is an analytics dashboard that has been collecting data on decentralized finance applications since 2020. The platform reads balances directly from the blockchains' smart contracts, converts them into US dollars at market prices and compiles them into rankings. What DeFi is in principle and how lending and exchange protocols work is covered in our guide to decentralized finance.
The core of DefiLlama is open: for each protocol there is a small program, known as an adapter, that defines which contracts are counted. These adapters are public in DefiLlama's adapter repository on GitHub, and anyone can review them and propose corrections. What each metric means is described in DefiLlama's methodology documentation. This openness is why exchanges, analysts and media cite DefiLlama as a reference.
On defillama.com you now find far more than TVL rankings: fees and revenue, trading volume on decentralized exchanges, stablecoins, yields in pools, bridges, funding rounds, token unlocks and a list of known hacks. The API delivers the basic data without a key, and heavy users can buy a paid Pro tier. Our analysis is based on the full dataset of November 3, 2026: 8,919 entries in the protocol list, 427 stablecoins and 15,900 yield pools. We compare further tools for market analysis in our overview of crypto analytics tools and platforms.
TVL on DefiLlama: what total value locked measures
TVL stands for total value locked. It is the dollar value of all coins that users have deposited in a protocol: deposits in lending protocols, liquidity in exchange pools, collateral for stablecoins. TVL is therefore a stock measure. It says how much capital trusts a protocol, but not how much the protocol earns or how often it is used.
The history reflects the market's cycles. In November 2021, DeFi TVL reached $177.5 billion; in October 2023 it fell to $36.0 billion. On November 3, 2025, the statistics showed $144.5 billion, at the start of 2026 still $111.9 billion, and on November 3, 2026, $81.8 billion.
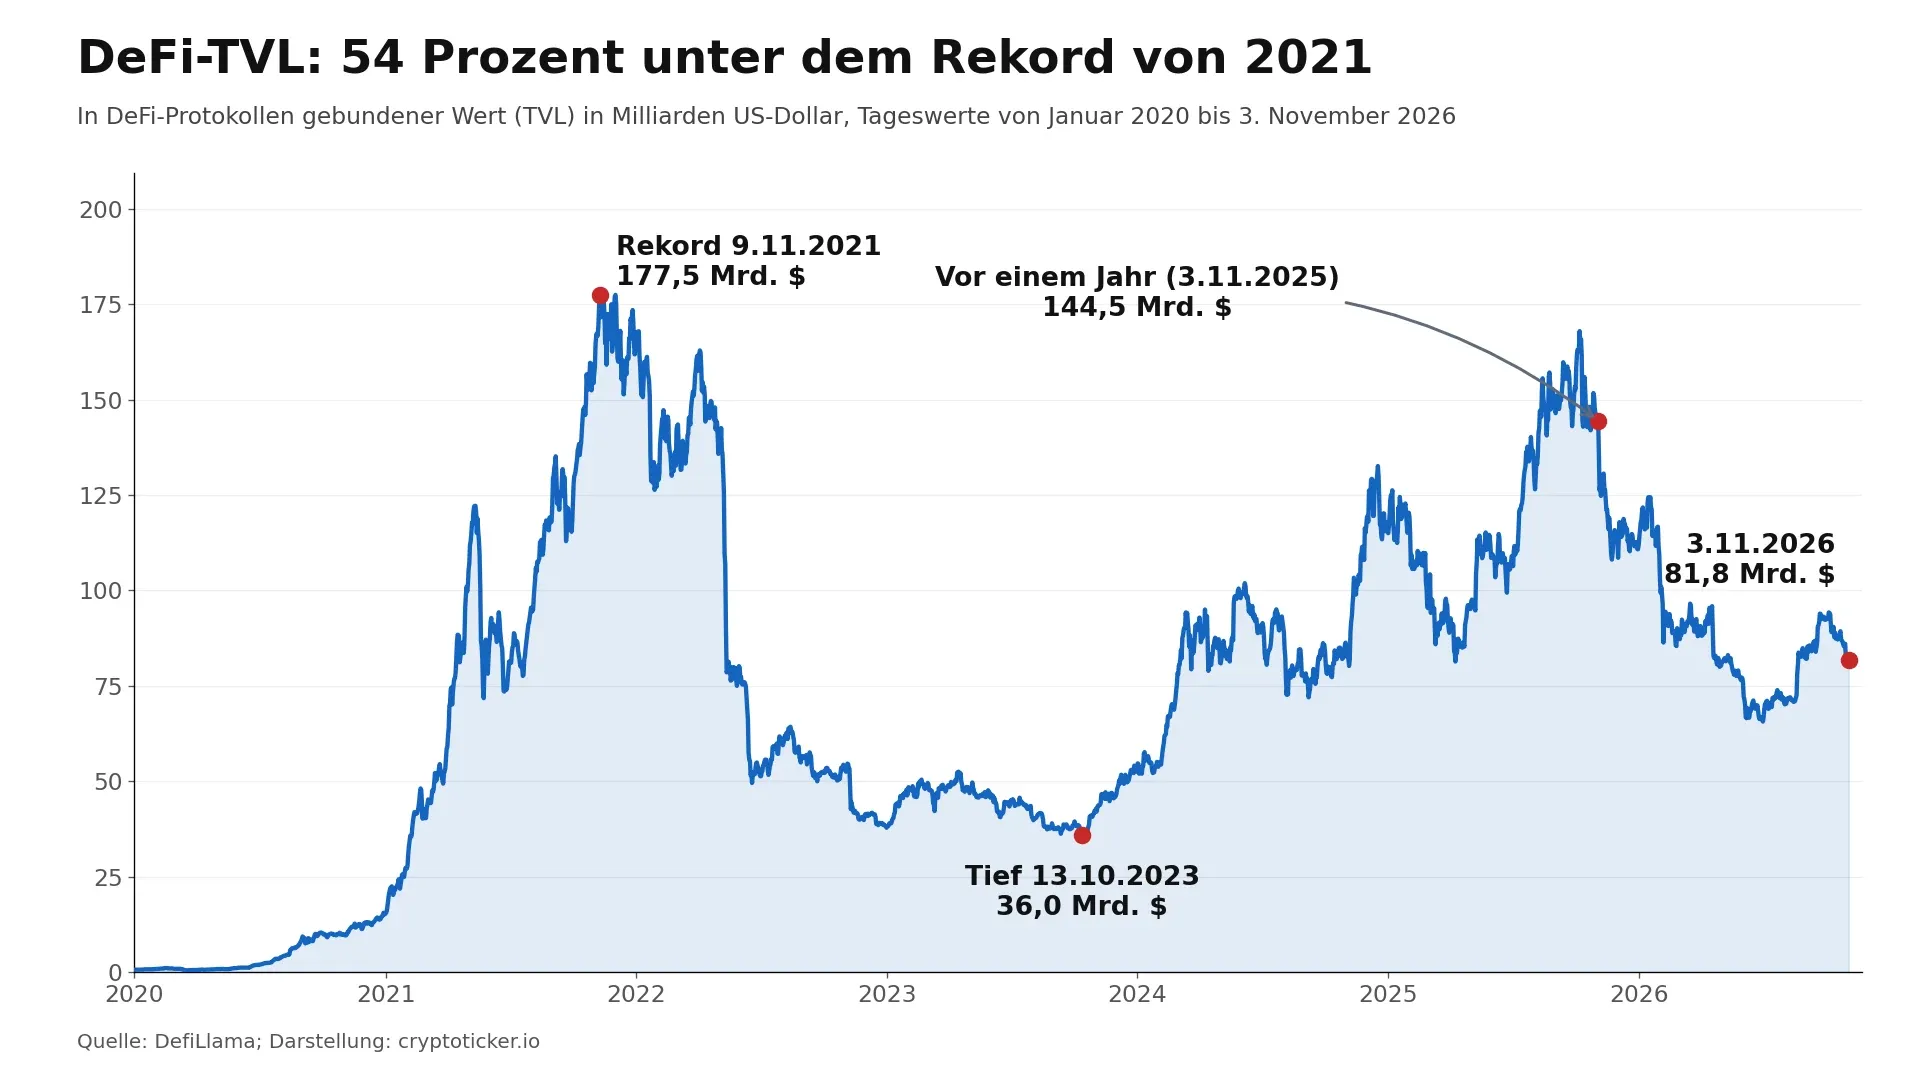
Total TVL of all DeFi protocols according to DefiLlama since 2020, excluding liquid staking and double-counted deposits
The distribution across blockchains is uneven. Ethereum holds more than half of the capital, followed almost level by Base, Solana, Tron and BNB Chain. Behind them come Bitcoin, the derivatives exchange Hyperliquid's own blockchain, Arbitrum, Robinhood Chain and Monad. How sharp outflows on a single blockchain can be is shown in our analysis DeFi loses 6.7 percent of its ETH deposits.
Blockchain
TVL in $bn
Share of DeFi TVL
Ethereum
43.65
53.2%
Base
5.87
7.2%
Solana
5.42
6.6%
Tron
5.22
6.4%
BNB Chain
5.18
6.3%
Bitcoin
4.09
5.0%
Hyperliquid L1
2.58
3.1%
Arbitrum
1.44
1.8%
Robinhood Chain
1.08
1.3%
Monad
0.91
1.1%
As of November 3, 2026. Source: DefiLlama. Share of the total across all 290 blockchains with locked capital.
Fees and revenue on DefiLlama: how to read them
DefiLlama separates two metrics that are often confused. Fees are everything users pay to a protocol: trading fees on a decentralized exchange, interest paid by borrowers, and at Lido the staking yield on deposited ether. Revenue is the part that stays with the protocol itself, landing in its treasury or flowing to holders of its token. The rest goes to the liquidity providers, depositors and stakers who supply the capital.
In the 30 days to November 2, 2026, users paid $2.27 billion in fees according to DefiLlama, 15 percent less than in the previous 30 days. Of that, $1.25 billion stayed with the protocols as revenue, just over half. How large the share is depends almost entirely on the business model.
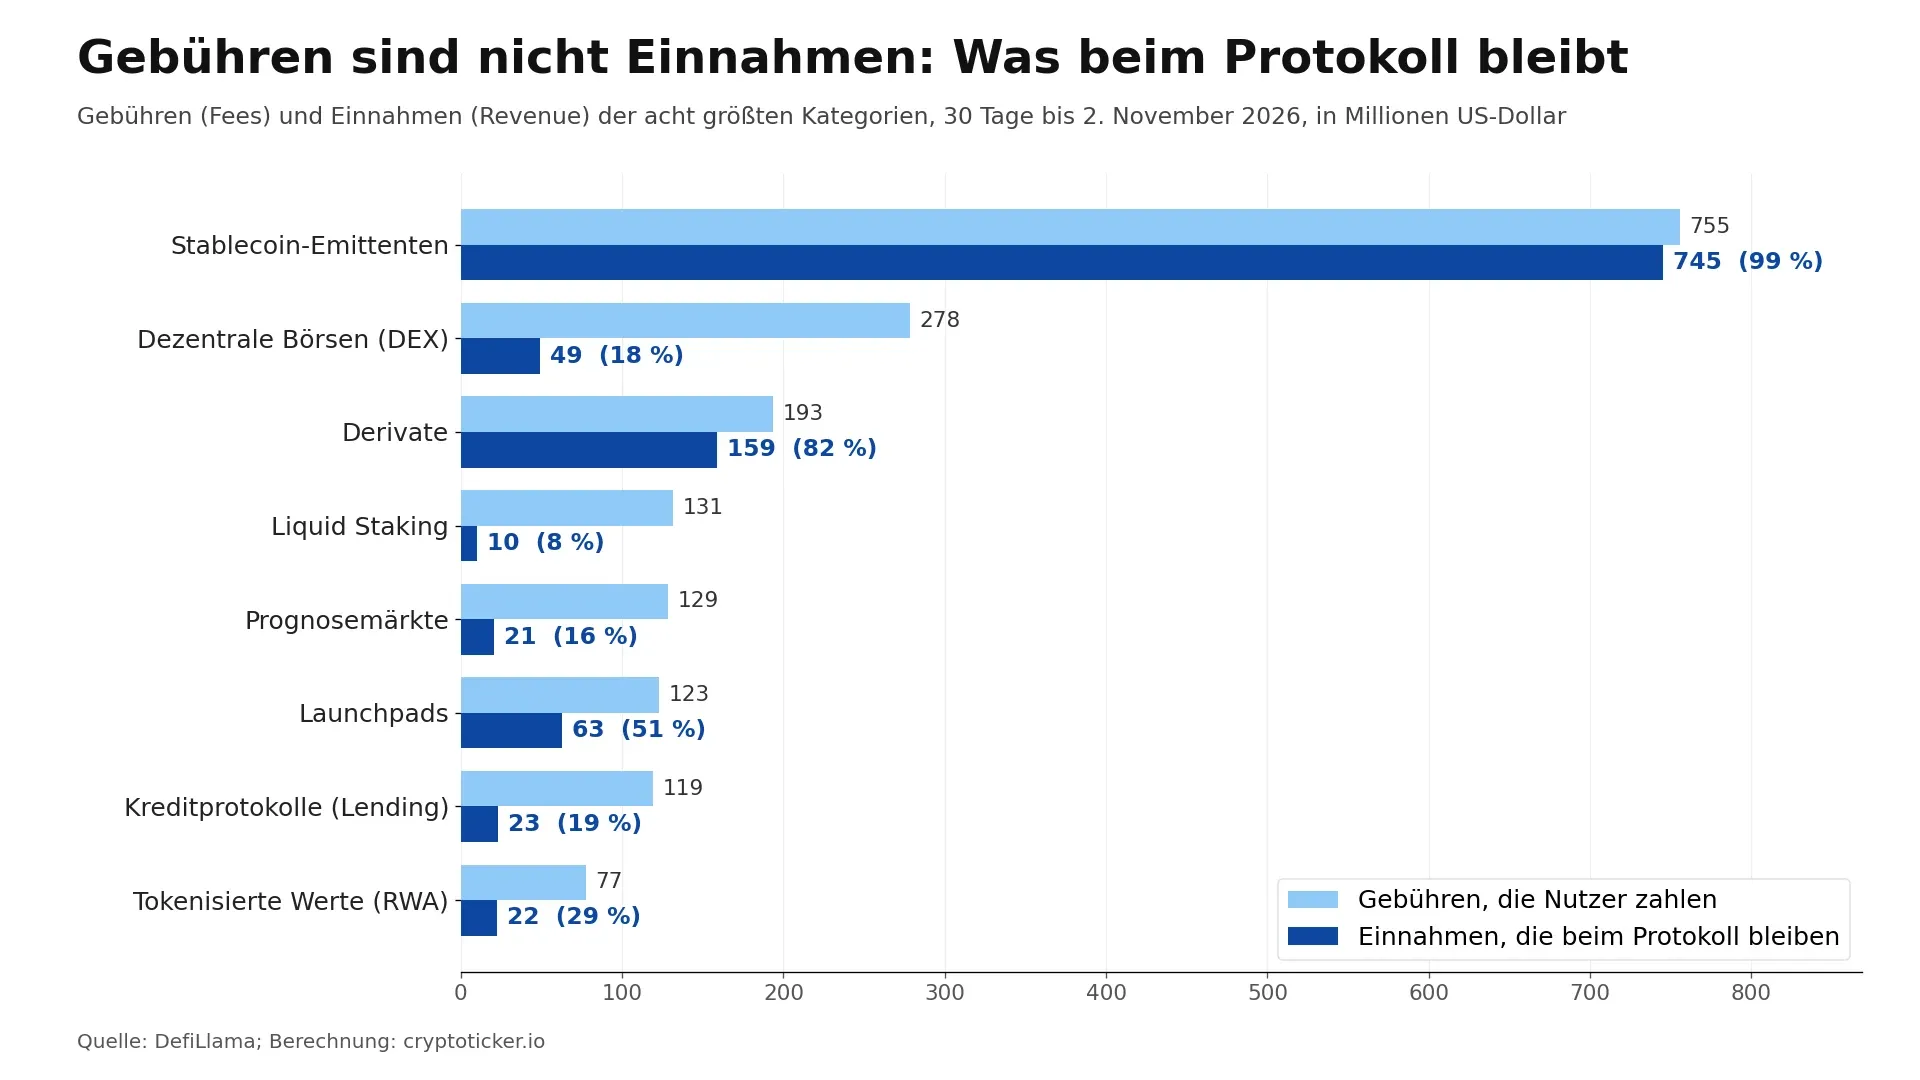
Fees and revenue by category on DefiLlama over 30 days
The top of the table is not occupied by DeFi protocols in the narrow sense but by stablecoin issuers. For Tether, DefiLlama counts the interest earned on reserves, mainly short-dated US Treasuries, as fees. Because Tether keeps all of that income, fees and revenue are equal. Lido is the reverse: according to its methodology, Lido keeps 10 percent of staking rewards and passes on the node operators' share from that, leaving about 6 percent as revenue. At Uniswap V4, all trading fees go to liquidity providers; at Uniswap V3, part has flowed into buybacks of the UNI token since December 28, 2025.
Protocol
Fees, 30 days
Revenue, 30 days
Share retained
Tether (USDT)
$520.4m
$520.4m
100%
Circle (USDC)
$207.8m
$207.8m
100%
Hyperliquid (perpetuals)
$78.6m
$62.0m
79%
pump.fun
$58.7m
$42.3m
72%
Lido
$57.5m
$3.5m
6%
Uniswap V4
$48.5m
$0.0m
0%
Aave V3
$36.8m
$4.7m
13%
Uniswap V3
$34.3m
$8.0m
23%
Sky Lending
$28.4m
$13.4m
47%
Morpho Blue
$24.9m
$0.0m
0%
30 days to November 2, 2026. Source: DefiLlama, selection of large protocols.
For investors, revenue is the more important number when it comes to the value of a token. At Hyperliquid, according to its methodology, 99 percent of fees flow into a fund that buys back HYPE tokens; a protocol with high fees and zero revenue, by contrast, earns nothing for its token holders. Revenue is not yet profit, though: DefiLlama does not deduct spending on development, security audits or reward tokens.
All users pay fees, but only the protocol keeps the revenue. Illustrative image, AI-generated
Stablecoins on DefiLlama: who dominates the market
In its stablecoin section, DefiLlama shows the circulating supply of every token pegged to a currency, broken down by blockchain. On November 3, 2026, dollar stablecoins worth $296.5 billion were in circulation, 2.5 percent less than a year earlier. Two issuers dominate the market: Tether and Circle together hold 84.2 percent.
Stablecoin
Supply in $bn
Market share
Backing according to DefiLlama
Tether (USDT)
178.51
60.2%
Fiat and bonds
USD Coin (USDC)
71.26
24.0%
Fiat and bonds
Sky Dollar (USDS)
6.49
2.2%
Crypto collateral
Dai (DAI)
4.71
1.6%
Crypto collateral
Ethena USDe
4.57
1.5%
Hedged crypto collateral
World Liberty Financial USD (USD1)
3.88
1.3%
Fiat and bonds
As of November 3, 2026. Source: DefiLlama. Market share of all dollar stablecoins.
Euro stablecoins play a small role in these statistics. All euro tokens combined came to $0.82 billion, 0.28 percent of the total stablecoin market. The largest is Circle's EURC with €502.6 million in circulation, followed by EURCV from Société Générale's subsidiary SG-Forge with €193.1 million. For investors in the EU, authorization also matters: Tether is not authorized under MiCA, and what that means for you is explained in our guide Tether (USDT) explained. Which stablecoins suit which purpose is shown in our stablecoin comparison.
Read circulating supply as a snapshot with a direction: a shrinking supply means more tokens are being redeemed than newly issued. What such a decline looked like for USDC is shown in our analysis USDC shrinks by $4.08 billion.
Yields on DefiLlama: how to find and check returns
The yields section lists returns from pools across all blockchains: deposits in lending protocols, liquidity in exchange pools, staking and vaults. For each pool, DefiLlama shows the annual yield (APY), split into a base yield from interest and fees and a reward paid in the protocol's tokens, plus the pool's TVL and flags for risks such as impermanent loss. On November 3, 2026, DefiLlama listed 15,900 pools, 2,654 of them with at least $1 million in deposits.
Our analysis of these 2,654 pools shows a clear pattern: the higher the yield, the smaller the pool and the more often the return comes from reward tokens rather than real income. 97.8 percent of the capital sits in pools yielding less than 10 percent. Half of all pools paid less than 2.17 percent. The largest single pool, staked ether at Lido with $21.8 billion, returned 2.28 percent.
Yield (APY)
Number of pools
Total capital
Typical pool size (median)
Share of pools where reward tokens dominate
below 5%
1,849
$122.56bn
$4.3m
7%
5 to 10%
472
$15.21bn
$4.3m
15%
10 to 20%
188
$2.34bn
$3.2m
16%
20 to 50%
108
$0.67bn
$2.9m
17%
50% and above
37
$0.13bn
$2.3m
27%
As of November 3, 2026. Source: DefiLlama, pools with at least $1 million in deposits; calculation: cryptoticker.io.
For stablecoins the picture is calmer. The 327 stablecoin pools with at least $10 million in deposits paid a median of 4.14 percent, of which 3.46 percent was base yield. Higher figures come almost only with leverage, reward tokens or less proven protocols; how quickly such a loop turns negative we work through in sUSDe yield versus Aave borrowing rate. If you are looking for staking through a regulated provider, you will find terms and licenses in our comparison of the best staking platforms.
Most DeFi yields are small; high numbers flow into small pools. Illustrative image, AI-generated
Six reading mistakes on DefiLlama and how to avoid them
DefiLlama measures carefully, but each number answers only a specific question. These six mix-ups are the ones we come across most often in discussions and price analyses.
1. Mistaking price losses for outflows
TVL is stated in US dollars. If the ether price falls, TVL drops even when not a single coin leaves the protocol. Our calculation for Ethereum: on November 3, 2025 it held $82.1 billion; on November 3, 2026, $43.6 billion, a decline of 46.9 percent. Over the same period the ether price fell from $3,909 to $2,250. Measured in ether, locked capital fell only from 21.0 to 19.4 million ETH, or 7.8 percent. Most of the decline was a price loss, not a loss of confidence.
2. Adding protocol values into one total
Many deposits are passed on several times: ether is staked at Lido, the staked ether serves as collateral at Aave, and the stablecoin borrowed against it ends up in the next pool. If you add up the individual values of all protocols on Ethereum, you arrive at $144.6 billion. DefiLlama reports $43.6 billion for Ethereum, because the total excludes liquid staking at $39.5 billion, bridges at $25.4 billion, staking pools at $12.9 billion, restaking at $5.8 billion and double-counted deposits. You can toggle such items on in the settings; the default view avoids double counting.
3. Confusing exchange reserves with DeFi
DefiLlama also tracks the reserves of centralized exchanges so that investors can check their holdings. In the raw API list, Binance shows $124.8 billion, more than the entire DeFi market at $81.8 billion. These amounts are customer funds on an exchange, not DeFi capital, and do not belong in the DeFi total. DefiLlama therefore lists them in a separate overview.
4. Mistaking fees for profit
High fees show usage, but not what reaches a token. Uniswap V4 generated $48.5 million in fees over 30 days, and the protocol kept nothing as revenue. With tokens, always look at revenue and, on DefiLlama, also at the part that goes to token holders.
5. High yields with no source
We found yields of 50 percent or more in only 37 of 2,654 larger pools, with $0.13 billion in deposits between them. In more than a quarter of those, most of the yield consisted of reward tokens whose price can fall. Always check how much base yield remains, how large the pool is and how long the protocol has existed. What to do with your deposits after an attack on a protocol is covered in our report on the governance attack on Hifi Finance.
6. Confusing TVL with market value
TVL measures deposits in a protocol; market value measures what all tokens of a blockchain or protocol cost on the market. The two are only loosely related. Cardano is an extreme example: on October 20, 2026, $62 million in DeFi stood against a market value of $8.15 billion, and on November 3 DefiLlama counted only $52.8 million. The context is in our analysis Cardano's DeFi versus its market value. DefiLlama shows the ratio of the two directly on many protocol pages.
How to use DefiLlama in six steps
- Check the big picture: the home page shows total DeFi TVL and the protocol ranking. Set the period to one year to separate trends from daily swings.
- Choose a blockchain: the blockchain overview shows where the capital sits and which protocols lead on each blockchain.
- Read the protocol page: it contains the TVL history, fees, revenue, token metrics, security audits and a link to the methodology. Compare the TVL history with the price of the main coin to avoid mistake number 1.
- Compare fees and revenue: the fees and revenue rankings show which protocols are really used and which of them keep something.
- Track stablecoins: if supply grows, new money is flowing into the crypto market; if it shrinks, tokens are being redeemed.
- Filter yields: filter for stablecoins, set a minimum size of a few million dollars and sort by base yield rather than total yield.
If you want to analyze the data yourself, use the DefiLlama API: TVL, fees, stablecoins and yields can be pulled as tables and fed into your own calculations.
DefiLlama for investors: our verdict
DefiLlama is the best free tool for judging DeFi by numbers rather than narratives. The platform is open, fast and covers almost every protocol. Its value only emerges, however, when you read the numbers correctly: think of TVL in coins before dollars, look at revenue rather than fees, and sort yields by where they come from.
Our analysis shows a market that has shrunk sharply in dollar terms but has remained surprisingly stable when measured in coins. Most of the money is earned not by the well-known DeFi protocols but by stablecoin issuers. And large stablecoin pools typically pay around 4 percent a year; anything well above that calls for close scrutiny. If you want to buy coins for DeFi, you will find licensed providers in our comparison of regulated crypto exchanges.
DeFi applications carry technical risks up to a total loss, for example from smart contract bugs or attacks. This guide is not investment advice.