Quick Overview Wednesday brings the August Personal Consumption Expenditures inflation report, marking the first inflation data release following the Federal Reserve’s September interest rate
Quick Overview
- Wednesday brings the August Personal Consumption Expenditures inflation report, marking the first inflation data release following the Federal Reserve’s September interest rate increase.
- Friday’s September employment report is projected to show 100,000 new positions added, with the jobless rate anticipated to remain steady at 4.2%.
- Micron Technology releases its fiscal fourth-quarter financial results on Wednesday, with Wall Street analysts projecting earnings of $31.52 per share and revenue approaching $51.07 billion.
- Additional earnings releases from CarMax, Carnival, Nike, and Accenture will provide insights into both consumer trends and corporate expenditures.
- Last week saw the 10-year Treasury yield finish at 5.17%, while mortgage borrowing costs reached their peak levels since January 2025.
Wall Street begins this week with attention squarely on inflation metrics, employment figures, and a series of important earnings announcements. The three primary market indexes all posted gains during the previous week. The Nasdaq finished trading near an all-time high, while the Dow ended a three-week decline.
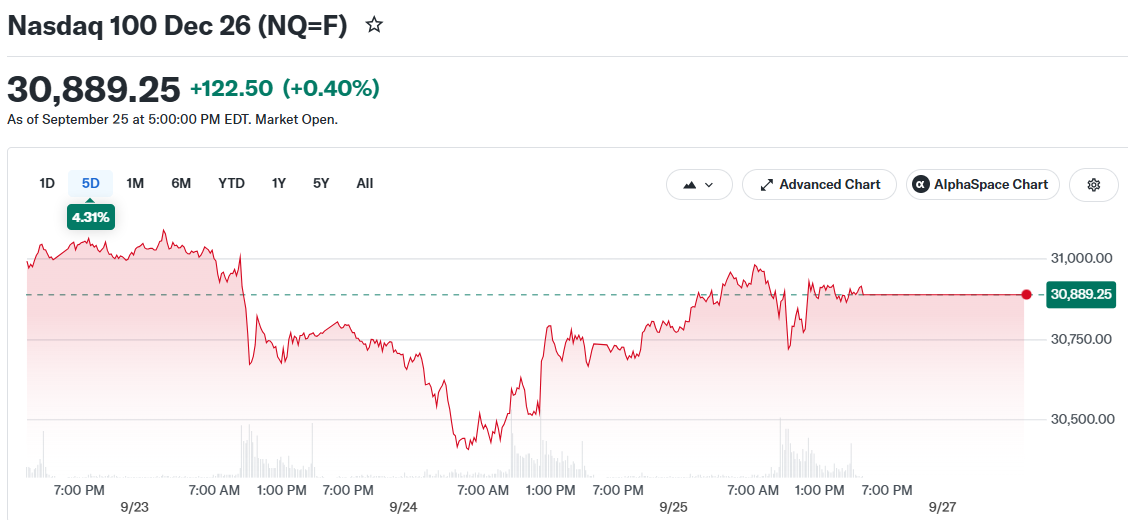 Nasdaq 100 Dec 26 (NQ=F)
Wednesday will see the Bureau of Economic Analysis publish the August Personal Consumption Expenditures price index. This metric serves as the Federal Reserve’s favored inflation measurement. Additionally, this marks the initial inflation data since the central bank implemented its interest rate increase on September 16.
The previous report showed Core PCE climbing 3.3% on an annual basis. This figure remains considerably above the Fed’s 2% objective. An inflation reading that exceeds expectations could increase the likelihood of an additional rate hike in October.
Employment Numbers and Consumer Sentiment Under Scrutiny
Tuesday brings an update to the Conference Board’s Consumer Confidence Index. The index experienced a decline in August, despite Americans reporting marginally improved perceptions of employment conditions.
Friday’s September employment report is anticipated to show 100,000 new positions created, according to economists polled by Reuters. The jobless rate is projected to hold steady at 4.2%.
While August’s hiring numbers exceeded projections, the gain wasn’t substantial enough to alter the modest hiring and limited layoff trend observed throughout this year. A jobs report that surpasses expectations could strengthen arguments for another Federal Reserve rate increase.
Consumer sentiment faces ongoing challenges. The University of Michigan’s survey revealed sentiment reaching its second-lowest point in the survey’s 74-year existence. Mortgage borrowing costs compound these pressures, with the 30-year fixed rate ascending to 7.45%, marking the highest level since January 2025.
Quarterly Results From Micron, CarMax, and Nike
Micron Technology unveils its fiscal fourth-quarter performance on Wednesday. Wall Street analysts project earnings of $31.52 per share with revenue totaling approximately $51.07 billion. As a memory chip manufacturer, Micron serves as an important indicator of demand connected to AI data center infrastructure.
CarMax announces fiscal second-quarter results on Tuesday. Earlier this year, an activist investor urged the retailer to evaluate price reductions on pre-owned vehicles. The earnings release may indicate whether pricing pressures have diminished.
Carnival Corporation launches the week’s earnings cycle on Monday. Wall Street forecasts $1.35 per share on revenue totaling $8.39 billion. Cruise industry spending remained robust during the summer months despite some consumers reducing expenditures on alternative travel options.
Nike delivers fiscal first-quarter results Wednesday following market close. Analysts anticipate $0.44 per share with revenue of $11.33 billion. The athletic apparel giant’s previous quarterly report revealed a 12% decline in China-based sales.
Accenture releases earnings on Thursday, with analysts projecting $3.18 per share and revenue of $18.03 billion. The consulting giant recently established a five-year AI safety collaboration with Anthropic.
McCormick and Company also announces results Wednesday, with expectations of $0.76 per share on revenue approaching $1.98 billion. The spice manufacturer is planning a merger with Unilever.
Treasury Yields and Overall Market Environment
The 10-year Treasury yield concluded last week’s trading at 5.17%. The 30-year yield hit its highest point in over two decades. Elevated yields diminish the present value of companies’ future earnings streams.
Eight of the eleven sectors within the S&P 500 posted negative returns for September. An equally weighted calculation of the index declined approximately 4% during the month, illustrating how market advances have depended heavily on a limited number of large-cap technology companies.
Gold settled near $4,322.40, crude oil traded around $92.79, and Bitcoin concluded near $83,809. The VIX, which measures anticipated market volatility, dropped to 14.87.
Multiple corporations go ex-dividend during this week, including Cisco Systems, Deere, and Bristol-Myers Squibb. Market participants will evaluate this week’s employment and inflation releases alongside elevated bond yields to determine the market’s trajectory ahead.
The post Key Economic Reports and Earnings to Watch This Week: Jobs, Inflation, and Micron (MU) Results appeared first on Blockonomi.

