Nasdaq agreed on September 10 to invest $100 million in Payward, the parent company of Kraken, as the two companies deepen work on tokenized equities and round-the-clock market infrastructure
Nasdaq agreed on September 10 to invest $100 million in Payward, the parent company of Kraken, as the two companies deepen work on tokenized equities and round-the-clock market infrastructure.
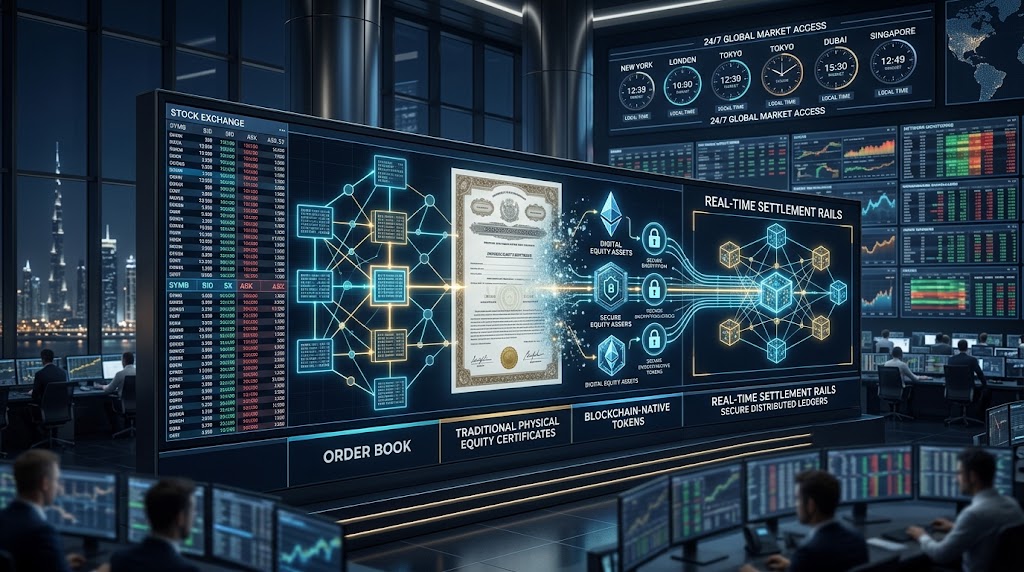
The investment is not a generic crypto bet. Nasdaq and Payward are already developing Nasdaq Equity Tokens, or NETs, with the goal of connecting regulated equities to Payward’s xStocks ecosystem. Nasdaq says it expects the NETs design to launch in the second quarter of 2027.
That puts the deal in a different category from the tokenized-stock experiments that simply wrap a share and trade the wrapper somewhere else. The stated objective is to preserve issuer control, shareholder rights, governance and market integrity while allowing the asset to move across new rails.
The $100 Million Is Really an Infrastructure Commitment
Nasdaq Ventures is supplying the capital, but the operational relationship is broader. Payward will adopt Nasdaq market-surveillance technology across its portfolio of trading venues, while the companies continue building the commercial and post-trade infrastructure around NETs.
Payward contributes Kraken’s execution venue and the xStocks infrastructure layer. Nasdaq contributes regulated-market architecture, issuer relationships, surveillance and experience operating markets where ownership rights and corporate actions have to reconcile correctly.
Those are the parts tokenization announcements often skip. A token can be created in minutes. A functioning securities market also needs identity, custody, market surveillance, corporate actions, settlement, disclosure, investor rights and a legally authoritative record of ownership.
This Is Converging With What Regulators and Clearing Infrastructure Are Doing
The timing matters. On September 1, the U.S. Securities and Exchange Commission proposed modernizing transfer-agent rules to account for electronic communications and blockchain technology. Optimisus examined the proposal in The SEC Wants Companies to Be Able to Keep Their Share Register on a Blockchain.
The distinction in that proposal is fundamental. A blockchain entry can either represent a claim on a security recorded somewhere else, or the ledger can become part of the authoritative ownership record itself. The second model removes a layer of reconciliation and makes tokenization much closer to market infrastructure than to a crypto wrapper.
Optimisus also recently covered DTCC partnering with BitGo on tokenized treasuries and equities. Taken together, the Nasdaq-Payward investment, the SEC rule proposal and DTCC’s work point in the same direction: tokenization is moving toward the plumbing used by regulated markets.
The Rights Attached to the Token Matter More Than the Token
The market already contains several products described as tokenized stocks, but they are not economically identical. Some are collateralized representations. Some are debt claims referencing a share price. Some are derivatives. Others are designed to carry the underlying shareholder rights.
Nasdaq and Payward are explicitly framing NETs around preserving the rights and protections associated with the equity. That is important because the user experience can look nearly identical while the legal position underneath is completely different.
Optimisus covered the execution side of this market when Silhouette and xStocks launched RFQ trading for tokenized equities on Hyperliquid. The Nasdaq relationship pushes xStocks toward the opposite end of the stack: connecting crypto-native distribution to issuer-sponsored, regulated equity infrastructure.
Always-On Markets Create New Problems as Well as New Access
The commercial case for tokenized equities is obvious. Blockchain rails can support transfers outside traditional exchange hours, global wallet-based access and programmable settlement. But a security does not stop having a home market simply because a token trades 24 hours a day.
Corporate news can break while the primary market is closed. Reference prices can become stale. Liquidity can fragment across venues. Trading halts, voting deadlines, dividends and stock splits still need a consistent source of truth. Surveillance becomes more complicated when the same economic exposure moves across regulated exchanges, crypto venues and decentralized markets.
That is why the surveillance agreement may be as meaningful as the investment itself. If tokenized equities become a permanent asset class, they will need the boring infrastructure that mature markets already rely on.
Crypto and TradFi Are Approaching the Same Market From Opposite Directions
Crypto exchanges have spent 2026 adding stocks, tokenized equities and synthetic equity exposure. Optimisus reported that perpetual futures on traditional assets reached roughly $445 billion of monthly volume on one crypto exchange. Traditional institutions, meanwhile, are moving settlement, custody and ownership records toward blockchain-compatible infrastructure.
The two systems are no longer developing in parallel. Nasdaq investing directly in Kraken’s parent is evidence that they are beginning to share infrastructure.
The important milestone will not be the first NET trade. It will be the first time a tokenized share moves across venues, settles cleanly, preserves the shareholder’s legal rights and handles a real corporate action without requiring an off-chain workaround. That is the standard a tokenized capital market eventually has to meet.
Sources