SEC staff have drawn staking-token classification lines that omit cbETH and stETH, leaving holders of Coinbase's wrapped staking token and Lido's liquid staking token in a regulatory grey zon
SEC staff have drawn staking-token classification lines that omit cbETH and stETH, leaving holders of Coinbase's wrapped staking token and Lido's liquid staking token in a regulatory grey zone that raises unresolved questions about unwrap mechanics and exit liquidity.
What the SEC Staking-Token Categories Leave Out
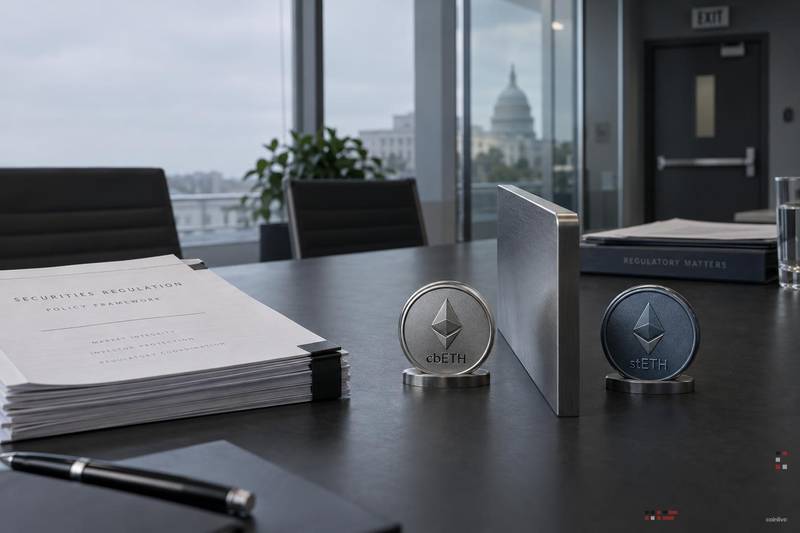
SEC staff guidance has begun carving out categories for staking-related tokens, but cbETH and stETH do not appear to fit cleanly within those defined categories, per CryptoSlate's reporting on the staff classification split. The exclusion is the central regulatory fact: neither token has been assigned a clear status, which is distinct from a ruling on validity or performance. For related coverage, see Bitcoin Faces $16B Options Expiry Before U.S. Data, CME Settlement.
cbETH is Coinbase's tokenised representation of staked ETH, issued when users deposit ETH into Coinbase's ETH2 staking programme. stETH is Lido's equivalent liquid staking token. Both trade on secondary markets at a discount or premium to spot ETH depending on redemption conditions and liquidity depth. When a regulatory framework does not address them, the classification gap itself becomes a risk variable for holders.
The SEC's public speech record on staking has evolved alongside the broader crypto regulatory posture, but no specific staff guidance yet names cbETH or stETH as compliant or non-compliant instruments. That silence creates uncertainty for platforms that list, custody, or facilitate redemptions of these tokens.
Coinbase Unwrap Mechanics and Potential Exit Risk
The headline question for cbETH holders is how an unwrap path would function if regulatory status remains unresolved. An unwrap, the process of redeeming cbETH back for underlying ETH, depends on Coinbase's operational capacity and any restrictions a regulator could impose on that redemption pipeline. Coinbase has faced ongoing regulatory friction across multiple product lines, adding operational context to the unwrap question.
For stETH, the exit path runs through Lido's withdrawal queue rather than a centralised exchange. Liquidity risk therefore differs structurally: stETH holders face queue depth and validator cycle constraints rather than platform-specific compliance decisions. These are distinct risk profiles that the SEC's category gap affects differently.
Classifying cbETH and stETH outside an established category does not automatically trigger enforcement, but it does mean any future guidance or rulemaking could apply to holders and platforms without a compliance roadmap already in place.
What cbETH and stETH Holders Should Watch Next
The most actionable signals to monitor are Coinbase communications about cbETH redemption terms and any updated language in SEC staff statements or no-action letters that explicitly name liquid staking tokens. A named exclusion would be materially different from current silence.
Secondary signals include the cbETH/ETH and stETH/ETH secondary market discount, which tends to widen when redemption uncertainty rises. Watch also for DeFi protocol borrowing limit adjustments against cbETH or stETH collateral, as lending platforms often price regulatory risk into collateral ratios before retail holders do.
This article does not constitute investment advice. Monitoring signals are informational only.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Cryptocurrency and digital asset markets carry significant risk. Always do your own research before making decisions.
Read original article on coinlive.me